


Analyzing Competitive Dynamics in the 5G Market Share
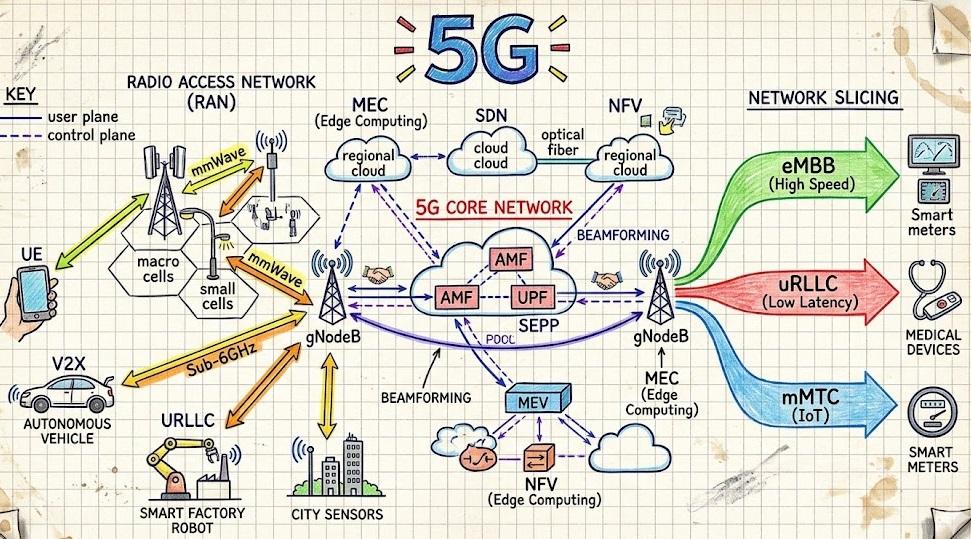
Dominant Players and Market Consolidation
The competitive landscape of modern wireless semiconductor manufacturing is characterized by intense rivalry among established microchip giants and agile wireless module specialists. Analyzing the 5G Market Share reveals a polarized environment where a few multinational semiconductor conglomerates control massive silicon production bases, while specialized module makers dominate regional integration verticals. Strategic mergers and acquisitions frequently reshape this hierarchy, as major electronic component suppliers absorb nimble wireless startups to acquire proprietary radio designs, specialized low-power sleep modes, or advanced multi-protocol firmware stacks. This consolidation trend challenges independent vendors to differentiate themselves through superior radio sensitivity, uncompromising interoperability standards, or deep industry-specific software integrations. Enterprise buyers must carefully evaluate vendor stability, roadmap transparency, and supply chain risks when selecting long-term wireless partners to ensure product manufacturing continuity.
Strategies for Differentiated Positioning
To capture and retain meaningful market segments, emerging semiconductor and module vendors must cultivate unique value propositions beyond basic radio specifications. Differentiation often manifests through advanced multi-protocol support combining multiple wireless standards, specialized ultra-low sleep current ratings, or superior cross-platform compatibility with open-source automation platforms. Some providers focus on energy-harvesting reference designs, appealing directly to battery-less sensor manufacturers handling maintenance-free industrial deployments. Others prioritize real-time collaborative development toolsets that rival dedicated enterprise asset management suites, reducing firmware coding errors. By identifying underserved market niches—such as ruggedized agricultural soil sensors or explosion-proof industrial monitoring nodes—independent vendors can carve out profitable domains shielded from direct competition with broad-spectrum semiconductor monopolies.
Customer Retention and Ecosystem Lock-In
Maintaining high customer retention rates is essential for sustaining market share within the fiercely competitive wireless module sector. Providers frequently employ ecosystem lock-in strategies, embedding their proprietary silicon SDKs, specialized commissioning tools, and matching gateway software development kits deeply into daily device manufacturing workflows. When smart hardware engineering teams rely on specialized custom firmware stacks, automated over-the-air update scripts, and integrated diagnostic tools tied to a specific manufacturer ecosystem, switching costs become prohibitively high. Consequently, vendors invest heavily in developer support portals, responsive application engineering teams, and continuous software enhancements to keep customer satisfaction high and churn rates minimal. However, growing industry alignment around open standards may encourage more fluid multi-vendor chip strategies, prompting vendors to compete increasingly on hardware efficiency rather than artificial proprietary barriers.
Strategic Partnerships and Channel Alliances
Collaboration between semiconductor manufacturers, smart home platform providers, and appliance OEMs plays a pivotal role in expanding market footprint and driving enterprise acquisition. Channel partners act as trusted advisors, bundling wireless microcontrollers, pre-certified RF modules, and reference software into comprehensive development packages for medium and large product manufacturers. Smart home ecosystem providers frequently bundle certified component guidelines with cloud onboarding tools, capturing vast consumer electronics markets efficiently. Strategic alliances also facilitate seamless interoperability between competing device types, enhancing overall user convenience and accelerating industry-wide standardization efforts like open connectivity specifications. These collaborative networks amplify marketing reach and enable smaller semiconductor developers to penetrate international markets that would otherwise require prohibitive localized sales operations.
Navigating Antitrust and Regulatory Pressures
The immense concentration of radio intellectual property and microcontroller manufacturing among a handful of dominant suppliers has attracted intense regulatory scrutiny worldwide. Antitrust authorities increasingly investigate licensing practices, cross-licensing bottlenecks, and unfair bundling strategies within the IoT semiconductor supply chain. Companies holding significant market share must navigate complex compliance landscapes, ensuring open access and fair licensing terms for regional hardware manufacturers and open-source automation projects. These regulatory interventions aim to foster a healthier, more competitive ecosystem where innovative wireless startups can emerge without facing insurmountable barriers erected by legacy semiconductor titans. Strategic leaders must remain adaptable, proactively aligning their corporate governance and manufacturing architectures with evolving legal expectations to mitigate compliance risks and sustain long-term enterprise trust.
➤ Latest Market Intelligence from Market Research Future:
Applicant Tracking Systems Market
Canada Applicant Tracking Systems Market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
